Ocean-related industries could generate more than $3 trillion in annual value by 2030, but startups still face a major financing gap as they move toward commercial scale.
The OECD projected that ocean-based industries could generate more than $3 trillion in annual value added by 2030, up from about $1.5 trillion in 2010.a The same projection estimated more than 40 million jobs in ocean-based industries by 2030.
The figure comes from the OECD's 2016 report, The Ocean Economy in 2030” and remains a widely used reference point for discussions of the sector’s economic potential. In 2010, ocean-based industries generated an estimated $1.5 trillion in added value.
Private investment in ocean-related industries has grown over the past several years. Data from the European Commission and independent research groups show growth in dedicated funds, corporate venture units, and blended public-private financing.
Fund Formation Increases
The European Commission's BlueInvest Investor Report 2026 maps 159 private funds active in the EU blue economy. Funds fully dedicated to the sector manage about €3 billion in assets, while funds with partial exposure to ocean-related industries hold an estimated €11 billion in private capital.
Venture capital firms make up the largest share of this investor base, according to the report. Most are not exclusively focused on ocean industries. Many hold broader mandates covering water, climate and sustainability-linked technology.
Research group Zero Carbon Analytics estimated the number of venture capital funds dedicated to the ocean rose from about four in 2018 to 40 in 2025. The BlueInvest report calls corporate venture capital participation in the sector "underutilised." The report argues that corporate investors can bring both capital and commercial market access to early-stage companies.
Growth rates differ by sector
OECD data show uneven growth projections across ocean-linked industries for 2010 to 2030. Offshore wind carries a projected compound annual growth rate of 24.5%.
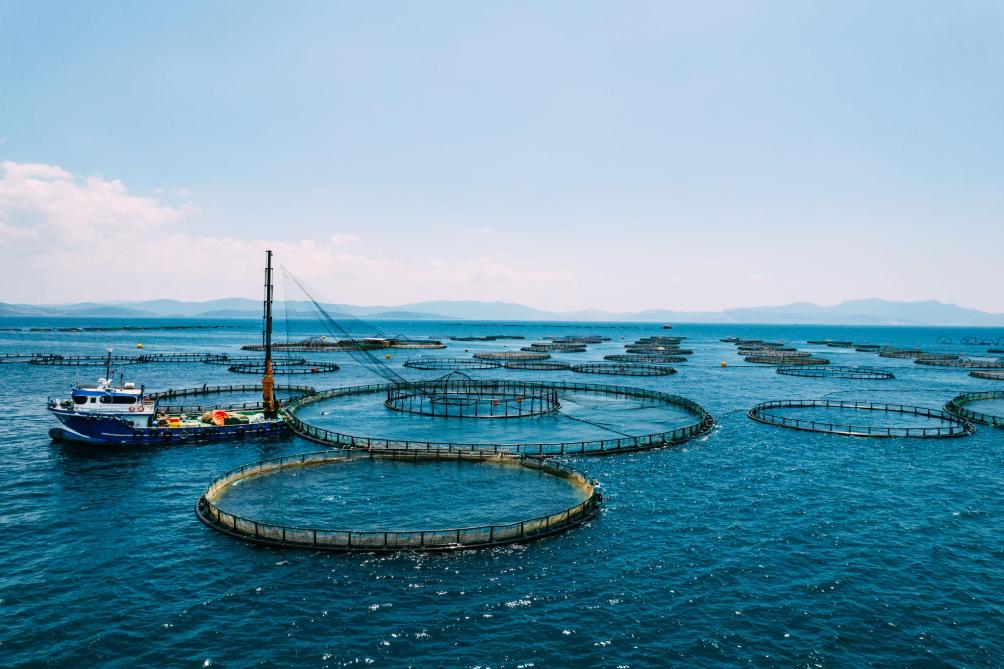
Fish processing is projected to grow 6.3% a year. Marine aquaculture is projected at 5.7%, port activity at 4.6%, and maritime tourism at 3.5%. The average across the ocean economy was projected at about 3.5% a year.
Some emerging ocean industries remain at earlier stages of commercialization. Deep-sea mining and ocean-based carbon removal, for example, face significant technological, regulatory and economic barriers, while marine biotechnology spans both established applications and emerging technologies.
Recent transactions
German aquaculture technology company Oceanloop secured up to €38.5 million in August 2026. The round combined new equity commitments from Hatch Blue's Blue Revolution Fund and Stolt Ventures with a €32 million venture-debt facility from the European Investment Bank.
Cultivated-seafood company BlueNalu raised $11 million in a round led by Agronomics, Siddhi Capital and Lewis & Clark AgriFood. The company develops cell-cultivated seafood as an alternative source of seafood supply.
Indian aquaculture technology firm AquaExchange raised $8 million in a Series B to expand its AI- and IoT-based tools for shrimp and fish farmers.
UK-based aquaculture technology company Aquabyte partnered with Vitruvian Partners in December 2025, with the investment firm acquiring a majority ownership position.
A gap at the growth stage
The BlueInvest program estimates €60 billion to €70 billion funding gap for the blue-economy small and midsize enterprises in the European Union. It attributes the gap to a shortage of late-stage private equity relative to early-stage venture capital.
The report says the constraint lies in moving technologies from pilot projects to revenue-generating operations, not in the availability of scientific research.
Public institutions continue to fund early-stage ventures in the sector. The report names national promotional banks and public financial institutions in Norway, the Netherlands, the UK and France as consistent investors. It says this backing helps attract private co-investment.
That public funding base has declined. That matters because public and development finance often plays a de-risking role in ocean projects before private investors enter on a larger scale. Global official development assistance fell 23% between 2024 and 2025, according to Zero Carbon Analytics. More than 95% of the decline came from reduced funding by Germany, the United States, the UK, Japan, and France. The OECD projects further reductions in 2026.
Outlook
Fund data and recent transactions show that private capital allocation to ocean-related industries has increased in recent years. The €60 billion to €70 billion gap between early-stage and late-stage financing identified by BlueInvest had not closed as of the report's publication.
Public funding that has historically supported early-stage de-risking has also declined. Growth rates vary across industries, with offshore wind projected to post a 24.5% compound annual growth rate, well above the 3.45% average across ocean-based industries.
The next phase of the blue economy may therefore depend less on proving that ocean technologies can attract early capital than on finding investors willing to finance the difficult transition from pilot projects to commercially scalable businesses.